Are You ERISA Compliant? Follow This Checklist
Key Takeaways A Quick Summary
Key Takeaways
- ERISA sets minimum federal standards for most private‑sector retirement and health plans and is enforced by the IRS, PBGC, and EBSA (DOL); government and church plans are generally excluded.
- Employers and plan fiduciaries have legal duties under ERISA; breaches or noncompliance can produce penalties, lawsuits, loss of qualified status, and forfeiture of tax benefits.
- There are specific disclosure and reporting obligations with firm deadlines—e.g., SPD (90 days), SMM (210 days), SAR (9 months), Form 5500 (7 months), COBRA notices (various short windows), RMD and Form 1099‑R deadlines.
- Common compliance failures include failing to provide an SPD, missing Form 5500 deadlines, poor recordkeeping, and late deposit of employee contributions; recommended remedies are organized calendars, training, automation, and using third‑party administrators.
- The Difference Card offers ERISA compliance services (unlimited plan documents, amendments, nondiscrimination testing, wrap documents) plus benefits administration and health‑cost savings; they provide proposals to streamline compliance and reduce costs.
The Employee Retirement Income Security Act of 1974 (ERISA) sets the minimum standards for most retirement and health plans offered by private companies. It aims to protect employees' interests, preventing responsible entities from misusing a plan's assets. However, navigating compliance on your own can get complicated. It's easy to miss deadlines and lose documentation without an organized system.
As an employer, you have a fiduciary duty to meet the requirements, making you liable for mistakes. Noncompliance risks penalties, lawsuits, and disqualifications. You must always be ready for any potential audit. Learning the applicable rules for your offered benefits can help you strategize for compliance.
Key Takeaways
These most important reminders can help you better navigate ERISA requirements:
- Definition and governing agencies: ERISA sets the minimum federal standards for most private-sector retirement and health plans. It's enforced by the Internal Revenue Service (IRS), the Pension Benefit Guaranty Corporation (PBGC), and the Employee Benefits Security Administration (EBSA), which is an agency within the U.S. Department of Labor (DOL).
- Covered benefits: ERISA-covered benefits include retirement plans and welfare benefits. Government- and church-offered benefits are excluded.
- Primary requirements: The DOL requires disclosures that necessitate ongoing administrative tasks. However, specific events also trigger certain requirements. These requirements center on providing comprehensive plan information to participants and beneficiaries.
- Noncompliance risks: Noncompliance can lead to costly penalties that often cost thousands of dollars per day. Participants also have the right to sue for their benefits.
How ERISA Works
ERISA contains a set of rules applicable to private employers providing retirement and welfare benefits. It requires companies to provide plan participants with detailed coverage information. The plans must also establish a grievance and appeals process that better enables participants to access their benefits. With ERISA, participants have the right to sue, especially when companies breach their fiduciary duty.
The following ERISA amendments have brought about additional requirements:
- Consolidated Omnibus Budget Reconciliation Act (COBRA)
- Health Insurance Portability and Accountability Act
- Newborns' and Mothers' Health Protection Act
- Mental Health Parity Act
- Mental Health Parity and Addiction Equity Act
- Women's Health and Cancer Rights Act
- Affordable Care Act
EBSA and the IRS are the authoritative bodies responsible for issuing and enforcing federal regulations covered by ERISA. EBSA is primarily responsible for the reporting, disclosure, and fiduciary requirements, while the IRS handles the participation, vesting, and funding requirements. PBGC is a federal agency created by ERISA to protect pension benefits.
Covered Employers
ERISA covers private-sector employers, regardless of size, that offer a retirement or welfare benefit plan. It excludes plans offered by government entities and churches, and plans maintained solely for compliance with unemployment, workers' compensation, or disability laws.
Note that ERISA does not require companies to offer retirement programs. Instead, it requires companies that offer those benefits to run the programs in a transparent way. Consequently, ERISA doesn't apply to employers who don't offer the covered benefits.
Covered Plans
ERISA-covered plans include most private-sector retirement and health and welfare benefit plans, such as:
- Defined benefit and contribution plans.
- 401(k) plans.
- Deferred-compensation plans.
- Profit-sharing plans.
- Health maintenance organization plans.
- Health reimbursement arrangements.
- Flexible spending accounts.
Since ERISA doesn't cover plans offered by government entities and churches, many 403(b) plans are excluded.
ERISA Compliance Checklist
ERISA's regulations center on keeping employees informed of their retirement program eligibility and plan status. Your key responsibility as an employer is to provide detailed disclosures to covered employees and beneficiaries, which include timely notices of plan amendments.
- Basic disclosure requirements for pension and welfare benefit plans.
- Additional requirements for welfare benefit plans offered as group health plans.
- Additional requirements for retirement plans.
Ongoing training can help your team stay on top of regulatory changes and meet your fiduciary responsibility. Creating a compliance checklist for each benefit can also keep you audit-ready. Working with third-party administrators can streamline the entire compliance process.
Basic Disclosure Requirements and Deadlines
The DOL lists basic disclosure requirements you must meet within a specific time frame:
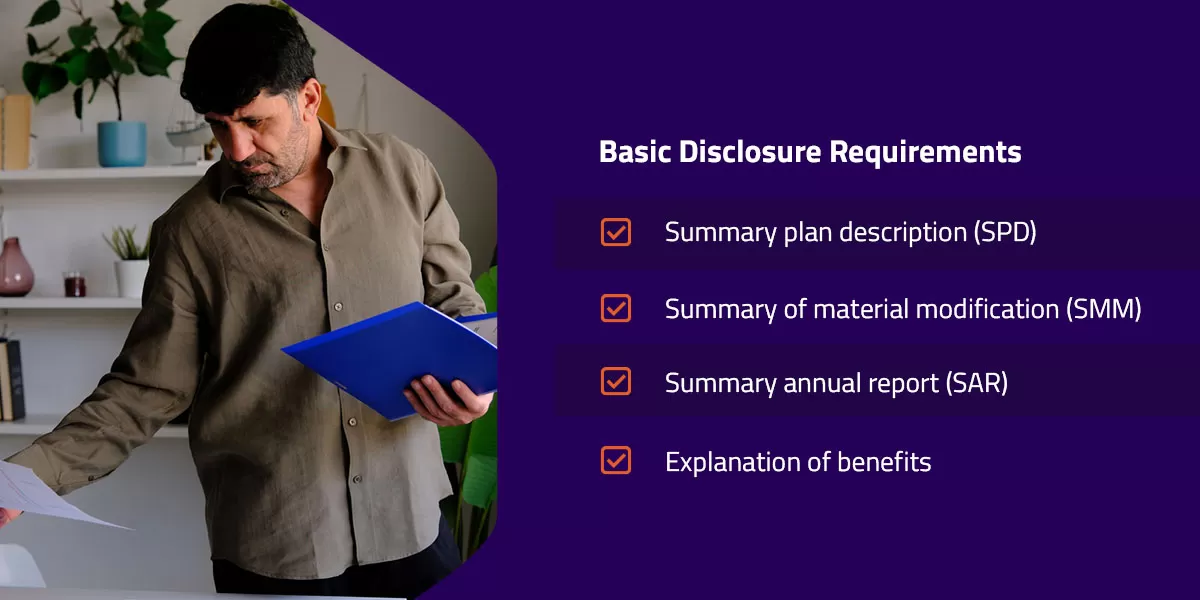
- Summary plan description (SPD): An SPD contains the benefits information and how the plan operates. Provide this SPD to participants within 90 days of becoming covered, and to beneficiaries within 90 days after first receiving the benefits. The SPD must accurately contain the plan details — there should be no outdated information from more than 120 days before you initially distribute the document.
- Summary of material modification (SMM): The SMM discusses plan modifications. Distributing an updated SPD satisfies this requirement. Otherwise, you must provide an SMM to participants and beneficiaries within 210 days after the end of the plan year.
- Summary annual report (SAR): The SAR summarizes the Form 5500, which is an annual return that certain direct filing entities and plan administrators use to satisfy reporting obligations. Complete the form if you're a covered entity or if you offer small or large pension or welfare plans. Provide participants and beneficiaries with the SAR within nine months after the end of the plan year or two months after the Form 5500 deadline.
- Explanation of benefits: An explanation of benefits discusses how the plan makes decisions regarding claim submissions. Requirements differ based on the plan and claim type.
You must provide copies of certain documents to participants and beneficiaries upon request, which can include the latest SPD, Form 5500, and other instructional documents. You have 30 days to provide the documents after a written request. Ensuring compliance with ERISA calls for an organized calendar. Make sure to have a system that tracks deadlines when an event or request triggers them.
Additional Disclosure Requirements for Welfare Benefit Plans
ERISA establishes additional requirements for welfare benefit plans that are group health plans. Specific coverage and life changes trigger these disclosures. ERISA compliance services make navigating the varying deadlines easier. Examples of additional requirements include:
- Summary of material reduction in covered services or benefits: This document explains amendments to a group health plan or SPD, such as premium increases. Provide this summary to participants within 60 days after adopting the change.
- COBRA general notice: This notice informs employees and their spouses of their right to purchase a temporary coverage extension when the employee loses coverage due to a qualifying life event. Provide this notice when the group health plan coverage begins.
- COBRA election notice: This notice informs qualified beneficiaries that they can elect COBRA coverage after experiencing a qualifying event. Provide this notice to employees, their spouses, and their dependent children generally within 14 days after you or a beneficiary notifies the plan administrator of the event.
- Notice of unavailability of COBRA: This notice informs individuals that they're not entitled to COBRA coverage. You must generally provide this notice within 14 days after you're informed of the qualifying event.
Additional Disclosure Requirements for Retirement Plans
ERISA-covered retirement plans come with additional requirements. Examples of these requirements include:
- Periodic pension benefit statement or individual benefit statement: Generally, this document indicates the total benefits and nonforfeitable pension benefits, if any, and the earliest date the benefits become nonforfeitable. Deadlines vary per plan type.
- Suspension of benefits notice: This notice informs employees of the suspension of their benefit payments. Provide the notice during the first month or the payroll period in which benefit payments must be withheld.
- Notice of significant reduction in future benefit accruals: This notice details plan amendments to defined benefit plans and specific defined contribution plans that significantly reduce the rate of future benefit accruals, or eliminate or reduce early retirement benefits or retirement-type subsidies. Provide this notice within a reasonable time frame, generally 45 days before the amendment's effective date.
- Notice of failure to meet minimum funding standards: This notice informs participants, beneficiaries, and alternate payees of their failure to make the required installment or other plan contribution to satisfy the minimum funding requirement. Provide the notice within a reasonable time frame, unless a funding waiver was requested. Provide the notice within 60 days if the waiver was denied.
ERISA details more requirements for retirement plans. To ensure your covered plans remain compliant, working with a third-party administrator can help.
Other Deadlines to Track
Since the IRS is a governing authority of ERISA, take note of the following tax and benefits-related deadlines:
- Form 5500: Form 5500 is due on the last day of the seventh month after the plan year ends. You can request an extension through Form 5558.
- Form 5330: Form 5330 is a form you use to report and pay different excise taxes related to employee benefit plans. Form deadlines vary, which can generally be on the 15th day of the 10th month after the last day of your plan year or on the last day of the seventh month after the end of your tax year. Other deadlines apply.
- Actual deferral percentage (ADP) and actual contribution percentage (ACP): ADP and ACP tests are IRS nondiscrimination tests for traditional 401(k) plans. Failing the tests requires corrective action, which is due within two and a half months after the plan year ends.
- Required minimum distribution (RMD): The first RMD is due April 1 following the year the participant turns 73. Subsequent distributions are due every December 31.
- Form 1099-R: Form 1099-R reports the distribution of retirement benefits. You must provide this form to participants by January 31 and to the IRS by February 28 of the following calendar year.
Questions to Ask Yourself to Determine Compliance
To avoid feeling overwhelmed, asking yourself the following questions can help you evaluate your existing compliance strategy:
- Do you provide ERISA-covered welfare or health benefits to your employees?
- Do you already have a comprehensive plan document that satisfies ERISA requirements?
- If you already have an SPD, do you have a system for distributing it on time to covered employees?
- Have you made amendments to your SPD, and did you provide covered employees with the SMM?
- Do you offer plans that require a Form 5500, and do you track the filing deadline?
- Do you have a system for regularly completing and distributing an SAR?
- Are you ready to be audited by the DOL?
- Has an employee ever filed a claim for violations, and is your documentation ready to prove compliance?
Answering these questions can help you determine whether you are compliant with ERISA's requirements or whether you need to make changes to your compliance operations.
Noncompliance Risks and Penalties
Noncompliance comes with costly and significant repercussions, even if you've only accidentally broken the rules. Retirement plans can lose their qualified retirement plan status. Qualified accounts can also lose their tax benefits.
As an employer, you and your plan administrator have the fiduciary responsibility to ensure compliance. Breaching this fiduciary duty can lead to legal action from plan participants, separate from any DOL penalty.
DOL penalties usually get adjusted annually for inflation and differ based on the violated ERISA statute. Penalty examples include:
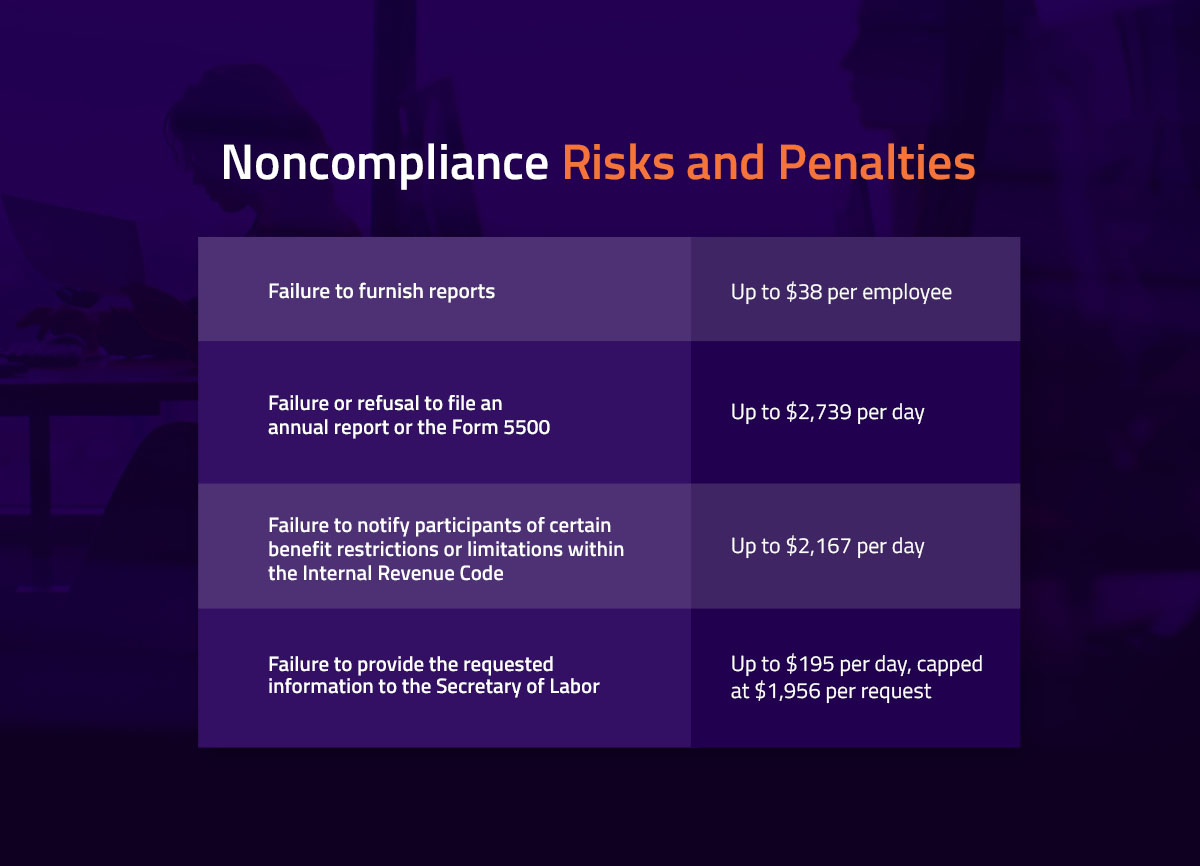
| Failure to furnish reports | Up to $38 per employee |
|---|---|
| Failure or refusal to file an annual report or the Form 5500 | Up to $2,739 per day |
| Failure to notify participants of certain benefit restrictions or limitations within the Internal Revenue Code | Up to $2,167 per day |
| Failure to provide the requested information to the Secretary of Labor | Up to $195 per day, capped at $1,956 per request |
Common Compliance Mistakes
When planning your compliance strategy, consider these common mistakes:
- Forgetting to provide an SPD: The SPD is your primary means to notify participants about their benefits. A carrier's benefits booklet doesn't always suffice, especially when it does not contain ERISA's legal provisions. Audits can easily show this compliance gap. An automated onboarding process that includes distributing the required documentation can make compliance easier.
- Missing the Form 5500 filing deadline: Form 5500 notifies the federal government about your plan's financial conditions and operations. However, tracking deadlines gets trickier as your company scales and as you offer multiple benefit plans. Your HR team must also understand which plans the form applies to — many mistakenly believe that it only applies to retirement plans, when it's also needed for health and welfare plans. Automated reminders can enable you to better navigate deadlines.
- Failing to organize compliance records: To fully comply with ERISA's regulations, you need comprehensive recordkeeping systems. Organized recordkeeping enables you to easily demonstrate compliance should a government agency ask for documentation. Fragmented systems are often inefficient, and document requests come with their own deadlines. Personnel changes can also make navigating compliance records difficult without a centralized system.
- Mishandling employee contributions: When employees contribute portions of their paychecks to their benefit plans, you must deposit the funds promptly into the plan trust according to ERISA's schedule requirements. Delays risk noncompliance, which can stem from administrative bottlenecks and disconnected systems.
Make ERISA Compliance Easy With The Difference Card
Navigating compliance can get overwhelming without the right system and support. Through our compliance services, we can help you meet the different ERISA requirements and protect you from costly penalties. You'll get unlimited plan documents, amendments, restatements, and nondiscrimination testing. We'll help you create wrap documents that satisfy ERISA, whether you offer Section 125, Section 105, or Premium Only Plans.
We don't stop at ensuring your compliance. At The Difference Card, we save employers an average of 18% on health insurance costs thanks to our customizable benefit solutions. You can create a custom medical expense reimbursement plan or opt for our benefits administration services. We offer health savings accounts, health reimbursement arrangements, flexible spending accounts, and other accounts that can cater to your employees' needs.
We've delivered $2.13 billion in employer savings throughout our 25 years of service. If you're ready to streamline ERISA compliance while improving your healthcare spending, request a proposal today.